

Inside China’s Machine · Where China’s Tokens Go, Episode 8
One judgment about China’s AI video and token demand is the one to test: the money sits with whoever controls the distribution and the compute contract, not with the studios that take the production risk. Set against the companies’ own documents, that clause splits in two. “Not with the studios” is supported, within limits. The claim that the money sits with distribution and compute is unproven. Keeping, in this piece, means margin, profit or cash retained after costs. Revenue is not keeping, and no document here shows any layer of the chain keeping the money from this demand.
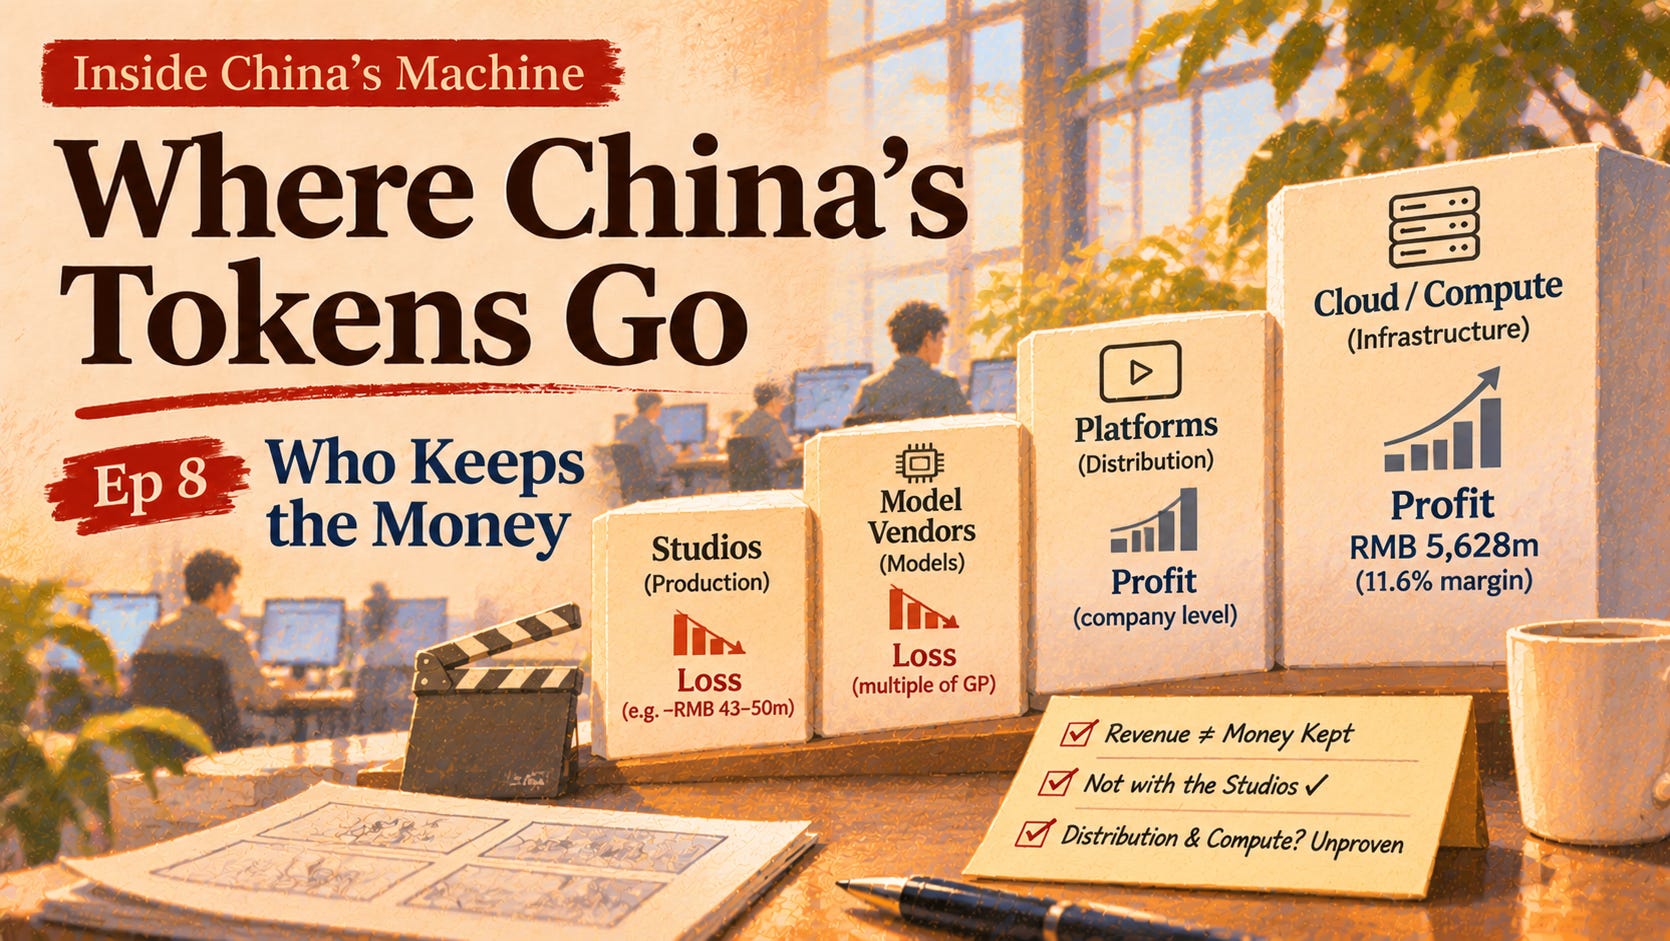
Take the strongest-looking number on the compute side. Alibaba’s Form 6-K of 20 August reports that its AI Cloud and Compute Services segment earned RMB5,628m of adjusted EBITA, a non-GAAP profit measure of the company’s own, on revenue of RMB48,437m in the quarter ended 30 June 2026. By our arithmetic that is 11.6% of segment revenue, against 7.2% a year earlier. The number is positive and rising, but it covers all of Alibaba’s AI cloud and compute services, including chips since a recast that quarter. The filing gives no margin on tokens, on model-as-a-service (selling access to a model through the cloud) or on inference (running a trained model to answer requests). A profit that wide cannot tell you what video and token demand left behind.
The studio side is narrower, because the filings say how much of each company the use represents. The short-drama line, together with derivative revenue where the filing combines them, was about 71% of first-half revenue at COL Group, 66% at Zhangyue, and AI short drama alone was 51.2% at Duiba. All three reported losses for the period, and each loss is a whole-company figure: RMB43.0m, RMB50.1m and RMB25.3m respectively. No studio filing read shows a retained profit on this use over the first half, apart from a small second-quarter profit at COL and an unaudited statement from Duiba about later months.
So the four layers report four different things. Clouds report segment profit on a wide base and cash going into a build-out. Model vendors report gross margins and net losses many times their gross profit. Platforms report whole-company profit, and studios report whole-company losses. None of these can be lined up against another, which matters if you are deciding where in this chain to put capital or a product, because each looks like a yield on AI demand and none of them is.